Financial Market Applications of LLMs
来源:Gradient · 发布于 2024/4/21
The AI revolution drove frenzied investment in both private and public companies and captured the public’s imagination in 2023. Transformational consumer products like ChatGPT are powered by Large Language Models (LLMs) that excel at modeling sequences of tokens that represent words or parts of words [2]. Amazingly, structural understanding emerges from learning next-token prediction, and agents are able to complete tasks such as translation, question answering and generating human-like prose from simple user prompts.
Not surprisingly, quantitative traders have asked: can we turn these models into the next price or trade prediction [1,9,10]? That is, rather than modeling sequences of words, can we model sequences of prices or trades. This turns out to be an interesting line of inquiry that reveals much about both generative AI and financial time series modeling. Be warned this will get wonky.
LLMs are known as autoregressive learners -- those using previous tokens or elements in a sequence to predict the next element or token. In quantitative trading, for example in strategies like statistical arbitrage in stocks, most research is concerned with identifying autoregressive structure. That means finding sequences of news or orders or fundamental changes that best predict future prices.
Where things break down is in the quantity and information content of available data to train the models. At the 2023 NeurIPS conference, Hudson River Trading, a high frequency trading firm, presented a comparison of the number of input tokens used to train GPT-3 with the amount of trainable tokens available in the stock market data per year HRT estimated that, with 3,000 tradable stocks, 10 data points per stock per day, 252 trading days per year, and 23400 seconds in a trading day, there are 177 billion stock market tokens per year available as market data. GPT-3 was trained on 500 billion tokens, so not far off [6].
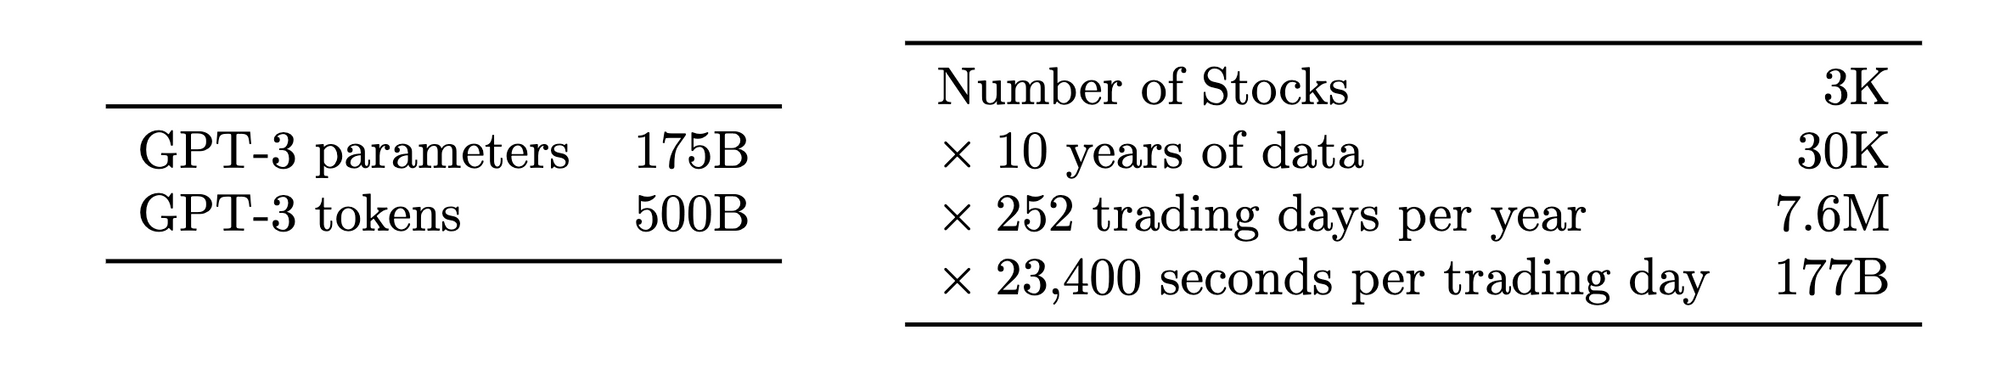 numbers courtesy of HRT 2023 NeuRIPS presentation
But, in the trading context the tokens will be prices or returns or trades rather than syllables or words; the former is much more difficult to predict. Language has an underlying linguistic structure (e.g., grammar) [7]. It’s not hard to imagine a human predicting the next word in a sentence, however that same human would find it extremely challenging to predict the next return given a sequence of previous trades, hence the lack of billionaire day traders. The challenge is that there are very smart people competing away any signal in the market, making it almost efficient (“efficiently inefficient”, in the words of economist Lasse Pedersen) and hence unpredictable. No adversary actively tries to make sentences more difficult to predict — if anything, authors usually seek to make their sentences easy to understand and hence more predictable.
Looked at from another angle, there is much more noise than signal in financial data. Individuals and institutions are trading for reasons that might not be rational or tied to any fundamental change in a business. The GameStop episode in 2021 is one such example. Financial time series are also constantly changing with new fundamental information, regulatory changes, and occasional large macroeconomic shifts such as currency devaluations. Language evolves at a much slower pace and over longer time horizons.
On the other hand, there are reasons to believe that ideas from AI will work well in financial markets. One emerging area of AI research with promising applications to finance is multimodal learning [5], which aims to use different modalities of data, for example both images and textual inputs to build a unified model. With OpenAI’s DALL-E 2 model, a user can enter text and the model will generate an image. In finance, multi-modal efforts could be useful to combine information classical sources such as technical time series data (prices, trades, volumes, etc.) with alternative data in different modes like sentiment or graphical interactions on twitter, natural language news articles and corporate reports, or the satellite images of shipping activity in a commodity centric port. Here, leveraging multi-modal AI, one could potentially incorporate all these types of non-price information to predict well.
Another strategy called ‘residualization’ holds prominence in both finance and AI, though it assumes different roles in the two domains. In finance, structural `factor’ models break down the contemporaneous observations of returns across
(摘要已截断,点击下方"查看原文"获取完整内容)
↗ 查看原文 / 完整内容
https://thegradient.pub/financial-market-applications-of-llms/
 苏公网安备32059002007950号